At a glance
- A virtual office is an address plus mail handling, sometimes a phone number and meeting room access. German providers advertise from a few euros a month to around fifty and upwards.
- The filing of a German company has to state a domestic business address, and it has to be one at which documents can actually be served. A post office box does not do it.
- Registering the company is the easy test. The harder one comes later, from the tax office, and it is not about your address in the abstract, it is about where the company is actually managed and whether it has a place of business.
- Three things get confused constantly and are not the same: the business address, the place of management (§ 10 AO) and a permanent establishment (§ 12 AO). Buying an address changes only the first.
- The useful question is not "is a virtual office allowed". It is "what can this particular provider actually demonstrate if an authority asks", and that is answerable in writing, before you sign.
What a virtual office actually is
A virtual office is a commercial product with no fixed definition. In the German market it usually means an address you may use for your company, post received at that address and forwarded or scanned, and often a phone number and some hours of meeting room use. Prices run from a few euros a month at the bottom of the market to around fifty euros and upwards for a package with scanning and rooms.
It is a legitimate product and there is nothing improper about it. The problem is not the product. The problem is that founders buy it to answer one question, what address goes in the register?, and then discover that three different authorities are asking three different questions, only one of which the address answers.
What the register needs
When a GmbH is filed, the filing has to state a domestic business address. That is the address that goes into the commercial register, appears in your imprint and is where anyone, a customer, a court, a creditor, will send documents.
The requirement behind it is practical: it must be an address at which documents can genuinely be served on the company. In German this is described as a ladungsfähige Anschrift, an address to which a summons can be sent. A post office box does not satisfy it, and neither does an address where nothing arrives and nobody is reachable.
Most serviced address providers can clear this bar, and that is why the sales pages stop here. It is the low bar.
Three things that are not the same
This is the distinction that decides everything else, and almost no comparison page draws it.
Business address
- The address in the commercial register and in your imprint.
- Must be domestic and capable of receiving service of documents.
- This is the one a virtual office sells you.
Place of management & permanent establishment
- § 10 AO: the place of management is where the centre of the company's senior management actually is.
- § 12 AO: a permanent establishment is a fixed place of business serving the company's activity.
- Neither is created by paying for an address. Both are questions of fact.
You can hold a perfectly valid registered address in Germany and still have your place of management somewhere else entirely, because that is determined by where decisions are actually taken, not by what is printed on your letterhead. For a founder who lives in India and runs the company from India, that is not a technicality. It is the central question about the company.
Where a cheap address runs into the tax office
The commercial register entry is not the end of the process. The company then has to be registered for tax, and that is where the address gets looked at properly.
An address used by a very large number of companies for post alone, with no rooms in regular use and nobody physically present, gives the tax office almost nothing to work with when it has to establish where the company is actually run. We are careful about how we put this, because the lawyer who reviewed our material was careful about it: this does not mean such an address "is not accepted". It means it can cause difficulty when an authority has to determine from where the business is actually managed, and in practice that can delay the tax number or the VAT ID.
Some tax offices go a step further and pass the file to a centrally competent office, because they do not see the place of management as being in Germany when the managing director holds no residence permit and is not here. We record that as our own observation from the formations we have handled, not as a general rule, but if it happens to you, it adds weeks, and no address package prevents it.
The pattern worth understanding is simple. An address is a claim. Rooms that exist, are used and can be visited are evidence for that claim. The cheaper the product, the less evidence comes with it, and evidence is exactly what is wanted at the point where a founder abroad is least able to supply anything else.
Where a virtual office works perfectly well
We are not going to tell you it never works, because that would be untrue and you would find out.
A virtual office is a sensible product when the company genuinely operates from Germany and simply does not need rooms, a consultant who works from home and wants their private address out of the imprint, a small online business, a company whose managing director lives in Germany and is contactable. In those cases the place of management is in Germany because the person running it is in Germany, and the address is doing exactly the job it is sold to do.
Where it gets thin is the case this site is mostly about: a company owned and directed from outside Germany, where the address is the only German thing about it. Then the address is being asked to carry weight it was never built to carry.
Eight questions to ask before you sign
These are answerable in writing. A provider who will not answer them in writing has given you the answer.
- How many companies are registered at this address? A number in the hundreds or thousands tells you what an authority will see.
- Are there real rooms at this address, and may I use them? If so, how, and at what cost.
- Who physically receives the post, and how quickly does it reach me? A person, or a forwarding arrangement.
- Can registered post and formal service of documents be accepted here?
- Is there a nameplate or a listing with my company on it?
- Have any of your clients had their tax registration queried because of this address? An honest provider will have an answer.
- Will you confirm in writing that I may use this address as the registered office? Notaries and register courts ask for this.
- What happens if I need someone here for an appointment? If the answer is nothing, then nothing is what you have.
Where we sit in this
We should be straightforward about our own position, because we sell something adjacent.
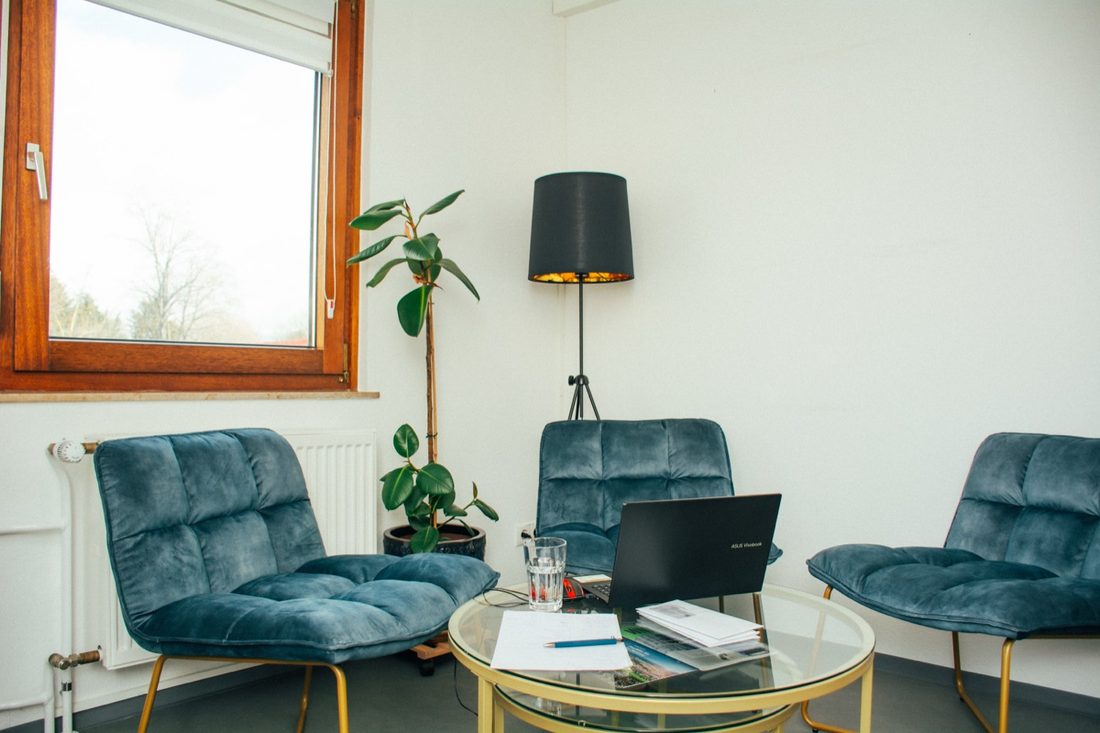
We are not a virtual office and we do not want to be compared as one on price, because we would lose that comparison, there are addresses in Germany for three euros a month and we are not going to match them. What we have is an office we actually occupy in Reutlingen, with people in it during business hours, meeting and workshop rooms that are used, and post opened by a person who can tell you what arrived and what it means.
For a founder in Germany who needs an address and nothing else, that is more than they need. For a company owned from abroad, whose tax registration will be looked at by someone trying to work out whether there is anything German about it, it is the difference between a claim and evidence.
The detail of what the address includes is on the business address page, and the rooms are on the Reutlingen page.
Questions
Sources
§ 8 GmbHG, contents of the filing including the domestic business address: gesetze-im-internet.de
§ 10 AO, place of management: gesetze-im-internet.de
§ 12 AO, permanent establishment: gesetze-im-internet.de
§ 20 AO, local competence for corporations: gesetze-im-internet.de
Written by Christoph Schuler
Founder, Business Center Reutlingen. Fifteen years in international automotive at Daimler,
two of them living in Bengaluru.
Published 29 August 2026
Business Center Reutlingen provides administrative and organisational support and introduces you to licensed professionals. We do not give legal or tax advice, in Germany only admitted lawyers (Rechtsanwälte) and tax advisors (Steuerberater) may do so.